Contents:
- Quick Answer
- Overview of the End Result
- What You’ll Need
- Numbered Steps
- Set Up an IRS Online Account
- Calculate Your Quarterly Estimated Payments
- Log Each Payment as You Make It
- Reconcile Quarterly Against Actual Income
- Review Your Full-Year Total Before Filing
- An Expert Quote
- A Seasonal Timeline
- Common Mistakes to Avoid
- FAQ
- What happens if I underpay my estimated taxes?
- Can accounting software automatically track estimated tax payments?
- Is it better to overpay estimated taxes to avoid penalties?
- Next Steps
The IRS penalty notice somehow lands in the mailbox before you’ve even finished celebrating a genuinely strong quarter, and it’s usually because estimated payments weren’t tracked carefully enough.
Quick Answer
Tracking business tax payments means recording each estimated payment date and amount, reconciling them against your actual quarterly tax liability, and using either accounting software or a dedicated IRS account to confirm receipt.
Overview of the End Result
A properly tracked tax payment system shows exactly what’s been paid, what’s still owed, and when the next payment is due, eliminating the guesswork that leads to costly underpayment penalties.
What You’ll Need
An IRS Online Account, your estimated tax voucher schedule, and either accounting software or a simple spreadsheet to log each payment as it’s made.
Numbered Steps
1. Set Up an IRS Online Account
Registering for an IRS Online Account lets you view your actual payment history directly, confirming the IRS received and correctly applied each estimated payment.
2. Calculate Your Quarterly Estimated Payments
Using last year’s tax liability or current-year projected income, calculate each quarterly payment due in April, June, September, and January.
3. Log Each Payment as You Make It
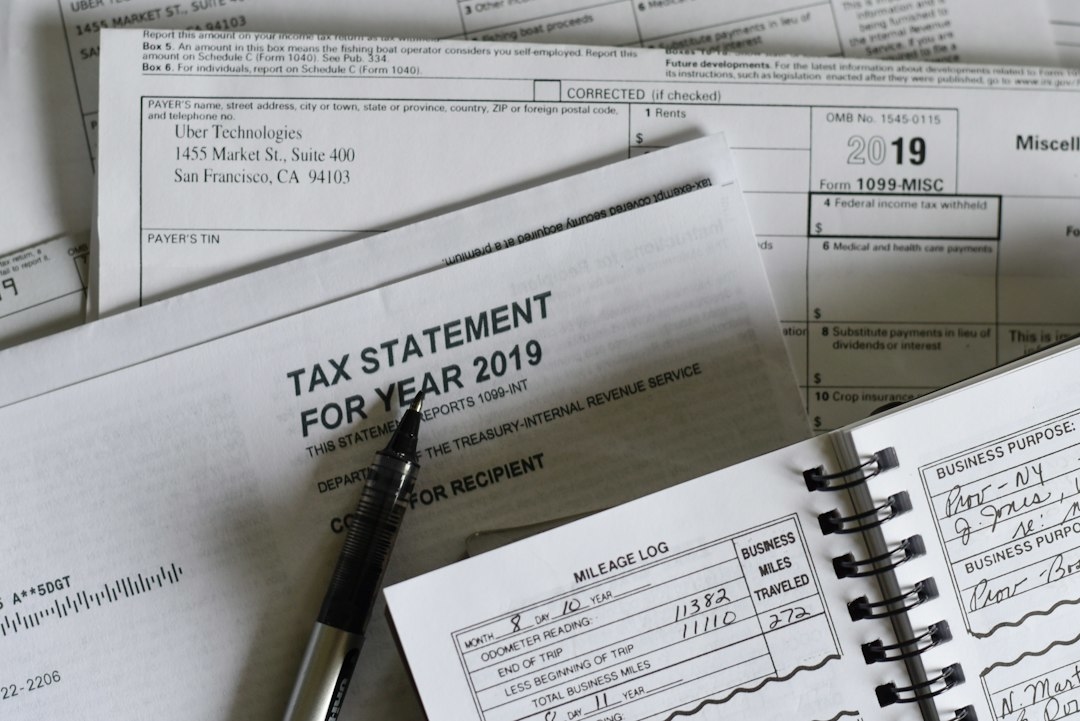
Recording the date, amount, and confirmation number for every payment in a simple spreadsheet creates a reliable backup record independent of the IRS system itself.
4. Reconcile Quarterly Against Actual Income
Comparing your estimated payments against actual quarterly income helps catch underpayment early enough to adjust the next quarter’s payment before penalties accumulate.
5. Review Your Full-Year Total Before Filing
Confirming total estimated payments against your final calculated tax liability before filing prevents surprises and clarifies whether you owe additional tax or are due a refund.
An Expert Quote
“Business owners who track payments quarterly rarely get hit with underpayment penalties,” notes tax advisor Rosalind Chukwu. “It’s the owners who wait until filing season to reconcile everything who end up scrambling.”
A Seasonal Timeline
Estimated tax due dates fall in mid-April, mid-June, mid-September, and mid-January, and marking these on a calendar well in advance prevents the common mistake of missing a deadline entirely.
Common Mistakes to Avoid
Business owners frequently base estimated payments solely on the prior year’s income, missing that a significantly stronger current year can still trigger penalties despite meeting prior-year safe harbor rules in some cases. Others forget to log confirmation numbers, leaving no record to dispute a payment the IRS claims it never received.
FAQ
What happens if I underpay my estimated taxes?
The IRS typically charges an underpayment penalty calculated on the shortfall amount and how long it remained unpaid, though meeting safe harbor thresholds can help you avoid this entirely.
Can accounting software automatically track estimated tax payments?
Yes, platforms like QuickBooks offer estimated tax tracking features, though many owners still cross-reference against their actual IRS Online Account for full confidence.
Is it better to overpay estimated taxes to avoid penalties?
Slight overpayment does avoid underpayment penalties, though significantly overpaying just ties up cash the business could otherwise use productively throughout the year.
Next Steps
Set calendar reminders now for all four upcoming estimated payment deadlines, and start logging each payment immediately rather than waiting until tax season to reconstruct the record.